Off the Grid: How Kazakhstan's Underground Capital Flows Are Generating Tenge Price Signals That No Terminal Can Capture
There is a version of Kazakhstan's currency market that appears in official statistics, central bank disclosures, and the data feeds that populate institutional trading desks across New York and Chicago. Then there is the version that actually moves the tenge on any given Tuesday.
The gap between these two realities is not incidental. It is structural, persistent, and—for traders who understand how to read it—surprisingly legible through a set of proxy signals that most US-based participants have never considered examining.
The Scale of What Doesn't Get Counted
Kazakhstan's informal economy is not a fringe phenomenon. Estimates from regional development organizations suggest that unrecorded economic activity accounts for somewhere between 25 and 35 percent of actual GDP, depending on the measurement methodology. Within that broader shadow economy, currency-related activity is particularly significant.
Three channels dominate. First, informal remittance networks connecting Kazakhstan's large labor diaspora in Russia, the Gulf states, and increasingly South Korea and Germany move substantial volumes of currency outside the formal banking system. These flows do not appear in the National Bank of Kazakhstan's balance of payments data with any precision. Second, grey-market currency exchange operations—some operating semi-openly in major cities, others functioning through mobile payment intermediaries—process transactions at rates that diverge meaningfully from the official interbank market. Third, unregistered trade financing, particularly along the China-Kazakhstan corridor, creates synthetic tenge demand and supply that has no corresponding footprint in customs or banking records.
For an algorithmic trading system calibrated to official data, all of this might as well not exist.
Why Institutional Data Feeds Miss the Signal
The problem is not that Bloomberg or Reuters are providing inaccurate information. The problem is that the information they provide is incomplete in ways that are systematically biased.
Official transaction data captures what flows through licensed financial institutions. In a market like the United States, where the informal economy is comparatively small and financial intermediation is nearly universal, this is a reasonable approximation of reality. In Kazakhstan, it is not.
When informal capital flows accelerate—say, during a period of ruble stress that pushes remittance workers to convert earnings more urgently, or when Chinese trading partners shift payment timing ahead of regulatory changes in Beijing—the tenge experiences demand and supply pressures that precede any official data release by days or sometimes weeks. Algorithmic systems that rely on published figures are, in effect, trading on yesterday's map in a market that has already moved.
This creates a recurring pattern: the tenge moves, institutional models fail to anticipate it, and post-hoc explanations cite factors that were visible in informal channels long before they appeared in any official dataset.
Reading the Proxy Signals
The practical question for US-based traders is how to detect informal flow dynamics without physical presence in Almaty or Astana. The answer lies in a set of proxy indicators that, while imperfect, carry genuine informational content.
Regional mobile payment volumes. Kazakhstan's mobile payment infrastructure, particularly through platforms that serve cross-border workers, shows volume patterns that correlate with informal remittance activity. Spikes in transaction frequency—visible in app store ranking data, third-party analytics services, and occasional operator disclosures—often precede tenge demand shifts by several days.
Cross-border rail and road freight data. The Kazakhstan-China trade corridor generates unofficial currency demand tied to unregistered shipment financing. Freight volume data from Kazakh logistics operators, while not perfectly granular, provides a directional indicator of whether informal trade financing is expanding or contracting in a given period.
Kazakh banking sector liquidity metrics. When informal flows are accelerating into the formal system—often because grey-market operators periodically need to clear positions through licensed banks—short-term interbank lending rates and overnight liquidity figures show characteristic patterns. A sudden tightening of overnight liquidity without a corresponding central bank action is frequently a sign that informal capital is being absorbed into the formal system in bulk.
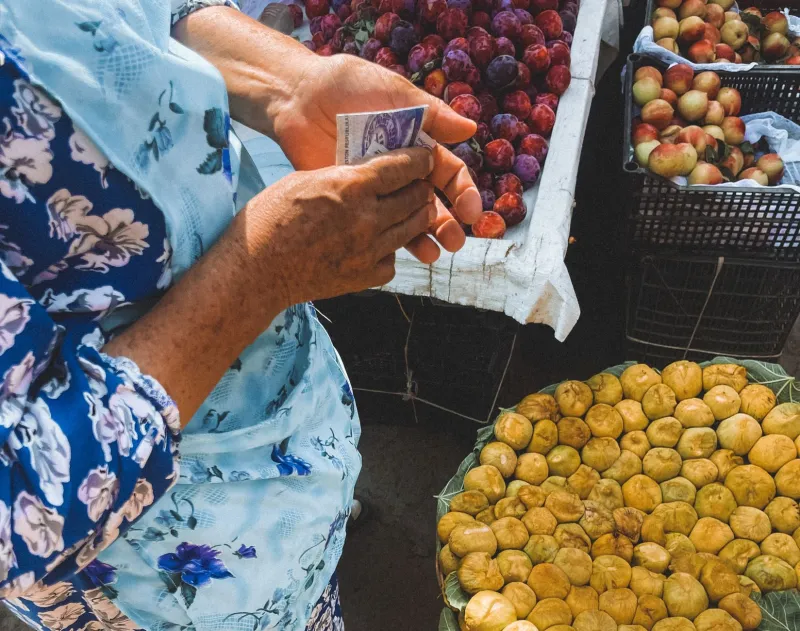
Commodity bazaar pricing in border regions. This is admittedly a more qualitative signal, but price differentials for dollar-denominated goods in border markets near Khorgos and Petropavlovsk have historically served as early indicators of informal exchange rate pressure. Several regional research services publish periodic surveys of these markets, and the data is more actionable than it might initially appear.
The Arbitrage Geometry
Understanding informal flows is not merely an academic exercise. It creates specific, tradeable inefficiencies.
When informal remittance pressure builds—typically identifiable two to four days before it reaches official transaction systems—the USD/KZT spread in the formal interbank market tends to widen slightly as liquidity providers anticipate incoming volume they cannot yet quantify. Traders who have already identified the informal flow signal can position ahead of this spread widening, then exit as the formal market absorbs the pressure and spreads normalize.
Similarly, periods of heavy informal trade financing along the China corridor tend to suppress the tenge's correlation with broader emerging market risk sentiment. During these windows, tenge pairs behave as if insulated from external shocks that are moving comparable currencies. For traders who recognize the mechanism, this temporary decorrelation is a signal to fade cross-asset EM positioning strategies that would otherwise apply.
The Information Asymmetry Argument
US institutional traders have significant advantages in most currency markets: superior technology, deeper research infrastructure, and faster execution. In the tenge market specifically, however, these advantages are partially offset by a structural information deficit that no amount of computational power can close if the underlying data inputs are incomplete.
The traders who have historically performed best in this market are not necessarily those with the most sophisticated models. They are those who have invested in understanding what the models cannot see—and built parallel monitoring systems around proxy signals that the formal data ecosystem ignores.
For US investors approaching the tenge as part of a broader emerging market or Central Asian allocation, this suggests a specific research priority: before optimizing execution or refining quantitative parameters, invest in understanding the informal flow landscape. The edge in this market is not algorithmic. It is epistemic.
Practical Limitations and Risk Considerations
None of this is without complexity. Proxy signals are inherently noisier than direct data, and the informal economy's behavior can shift in ways that invalidate historical correlations. Regulatory changes in Kazakhstan—the National Bank has periodically attempted to formalize grey-market exchange activity—can alter the relationship between informal flows and observable proxies without warning.
Additionally, US traders should be aware that engaging with counterparties who operate in informal market segments, even indirectly, carries compliance implications that require careful legal review.
The opportunity is real. So is the need for disciplined, well-advised implementation.
Conclusion
The tenge's shadow economy is not a bug in Kazakhstan's financial system. It is a feature of a market that developed under specific historical, geographic, and institutional conditions that differ fundamentally from the environments that shaped Western trading models. For US participants willing to engage with that complexity rather than paper over it, the informal flow landscape offers something increasingly rare in global currency markets: a durable, structural source of information advantage that sophisticated competitors have not yet systematically exploited.